AMD delivered the kind of results that the chip sector badly needed. The company beat third-quarter estimates, guided fourth-quarter sales well above forecasts and told investors it expects total revenue to grow by more than 80% in 2027, a projection that eased fears that the artificial intelligence boom is running out of steam.
A record quarter
Third-quarter revenue rose 45% to $13.38 billion, beating estimates of $13.09 billion, and adjusted profit came in at $2.09 per share against expectations of $1.95. Revenue was up from $9.25 billion a year earlier.
The data-centre business was the star. Data-centre revenue jumped 97% to a record $8.55 billion, exceeding estimates of $8.20 billion. The profitability story also improved. Non-GAAP gross margin was 56%, up 190 basis points from a year earlier.
The big number: 80% growth in 2027
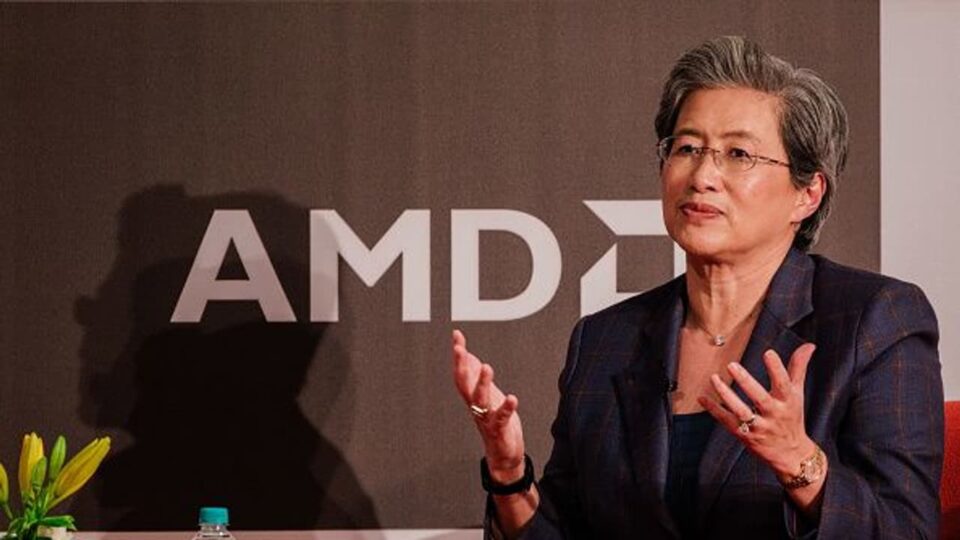
The forecast overshadowed the quarter itself. Chief executive Lisa Su said AMD expects overall revenue to rise more than 80% in 2027, above the 77% analysts had estimated, and that data-centre chips will account for about 80% of next year’s sales. That more than doubles AMD’s earlier long-term target of growth of 35% or higher.
Su added detail on what will drive it. She expects server revenue to double year on year in 2027 and growth in data-centre AI to accelerate faster than the company projected 90 days earlier. She also said demand currently exceeds supply, and she pointed to total cost of ownership as a key advantage for customers.
Near-term outlook
For the current quarter, AMD set a high bar. It expects fourth-quarter revenue of about $17 billion, plus or minus 3%, above Wall Street’s $16.29 billion estimate and implying roughly 66% annual growth. One note of caution: AMD anticipates an adjusted gross margin of around 55% next quarter, compared with 56% in the third
A weaker spot
Not every division performed. Sales in the client and gaming segment, home to PC chips and console processors, fell 8% to $3.72 billion, missing estimates of $3.79 billion. That shows how heavily AMD’s growth now depends on data centres, where it is challenging Nvidia.
Market reaction
Investors responded enthusiastically. The shares had risen 3.65% to $483.90 during regular trading, and then surged in after-hours trading. Gains reached about 8% in extended trading. Neocloud providers such as CoreWeave and Nebius also rallied on Tuesday and stayed higher after the report.
Analysts said the timing helped. A Goldman Sachs analyst noted that investor expectations had fallen after Intel’s weak outlook last week, which made AMD’s results and forecast more encouraging. Reuters framed the report as a strong counterpoint to mounting fears that the AI boom is losing steam.
Why it matters for the wider market
The AI trade has been under heavy pressure in recent weeks. Intel’s gloomy guidance, heavy borrowing by the biggest technology companies and weaker returns for some software groups raised doubts about whether spending can continue at its current pace. AMD’s numbers do not settle that debate, but they show customers are still ordering chips and are willing to commit to multi-year plans.
The company’s strategy is also notable. It has been building a full set of products, from server processors to AI accelerators, to give cloud customers an alternative to Nvidia. A forecast of growth above 80% suggests those efforts are being rewarded, though it also raises expectations. If supply constraints ease or customers reduce orders, a forecast this ambitious leaves little room for error.
What to watch
Investors will watch three things in coming months: how quickly AMD can ramp production to meet demand, whether margins hold as it scales, and whether major customers confirm their spending plans. Su’s confident tone offers reassurance for now. The test will come when 2027 begins.
