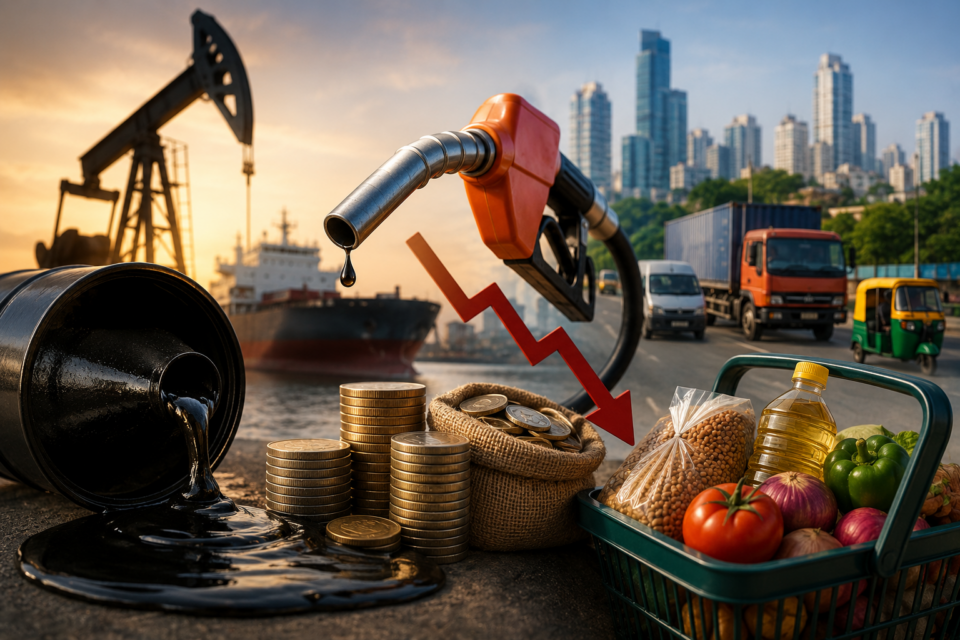
For most households, oil prices are not an abstract market number. At about $110 a barrel, a five-month high, they are showing up at the petrol pump, on winter heating bills, in the supermarket aisle and on the monthly mortgage statement. The pressure on household budgets from oil prices is now being felt in nearly every part of daily life.
At the pump and in the boiler room
Fuel is the most visible cost. Global diesel prices have reached record highs. The average pump price in Britain hit about £2.00 a litre this month, and the US price of diesel set a record of $6.53 a gallon in September. In the United States, a jump in petrol prices accounted for more than half of September’s acceleration in consumer prices.
Heating is next in line. Natural gas prices in Asia and Europe are at their highest since December 2022. Analysts estimate that heating bills in New York could be about 47 percent higher than last year, while British households face gas bills roughly 10 percent higher than a year ago this quarter.
For families on fixed incomes or tight budgets, those increases arrive just as the cold weather does.
The supermarket effect
Oil’s influence extends well beyond transport. Plastics are made from oil and gas, and packaging typically accounts for between 5 and 15 percent of the manufacturing cost of a grocery product. US plastic prices were up 7 percent in August compared with a year earlier.
Fuel also costs more for the trucks, ships and tractors that move and grow food. The United Nations’ Food and Agriculture Organization expects global food inflation to accelerate and to last well into 2027. Shoppers may notice it first in staples that depend heavily on energy and packaging.
Borrowing gets dearer
Perhaps the most lasting impact is on credit. Energy-driven inflation has pushed central banks towards a firmer stance, and bond yields have risen with it. In the US, the average 30-year mortgage rate has climbed from around 6.1 percent to about 7.5 percent. The Mortgage Bankers Association put it at 7.41 percent last week.
Higher rates are already cooling housing activity. US pending home sales dropped 7.3 percent in September, and mortgage applications have weakened again. In Australia, a separate report shows house prices fell in every capital city in the September quarter for the first time in 15 years, with a combined drop of 4.7 percent, the steepest quarterly decline on record.
Banks are adjusting as well. National Australia Bank said this week that it plans to cut 2,500 jobs, about 6 percent of its workforce, and Westpac announced further restructuring.
How families are coping
Practical responses are emerging, though none is painless. Drivers are combining trips and delaying non-essential journeys. Households are checking energy tariffs, adding insulation or draught-proofing, and switching suppliers where they can. Shoppers are trading down to own-brand goods and buying in bulk where storage allows.
Financial advisers generally suggest that anyone with a variable-rate loan, or a fixed term that ends within the next year, should review their options now rather than later. Speaking to a lender early can open up choices, such as extending the loan term or moving to a fixed rate, that disappear if payments are missed.
What would bring relief
The outlook depends heavily on events far from the kitchen table. Oil fell briefly this week on hopes of a US–Iran deal, then rebounded as attacks on shipping in the Persian Gulf continued. If a settlement holds, energy prices could ease and take some pressure off inflation and rates. If not, economists warn that “higher for longer” will apply to household bills as much as to central-bank policy.
Either way, the lesson from this autumn is that a spike in one commodity can travel a long way, from a tanker in the Gulf to a family’s mortgage payment.
